AI-generated summary
Europe has world-class science, talent and a market of 450 million people, yet it is losing ground in the semiconductor industry that underpins the digital economy. María Marced, former president of TSMC Europe, blames fragmentation across research, industry and procurement for weakening Europe’s ability to turn technological excellence into large-scale manufacturing and market power. She highlights AI as the next explosive wave of demand—potentially a $2 trillion market within a few years—where production of advanced AI accelerators is concentrated outside Europe. Marced chaired an industry advisory group whose recommendations—now informing the European Chips Act 2.0—call for tighter links between R&D, pilot lines, training and production, plus multi-year purchase commitments from sectors like automotive, telecoms and defence to create stable demand that justifies major manufacturing investments.
Marced underscores practical steps to reverse the trend: build clusters that aggregate companies and capabilities, scale pilot lines so prototypes can be validated before tape-out, and align vocational training with factory needs. She points to Dresden’s TSMC-led fab as a model where customers, suppliers, talent and public support converge, and to Spanish strengths in photonics and power electronics as opportunities. The core message: convert European demand into industrial commitment through coordinated procurement, sustained funding, and cross-border collaboration to create jobs, technological autonomy and a stronger position in the global semiconductor value chain.
In the webinar led by Juan Moreno, CEO of the Foundation, María Marced analyses how to connect the European demand for chips with its industry. Customers, pilot lines, training and sustained financing lead the way, with Dresden and the PERTE Chip as examples.
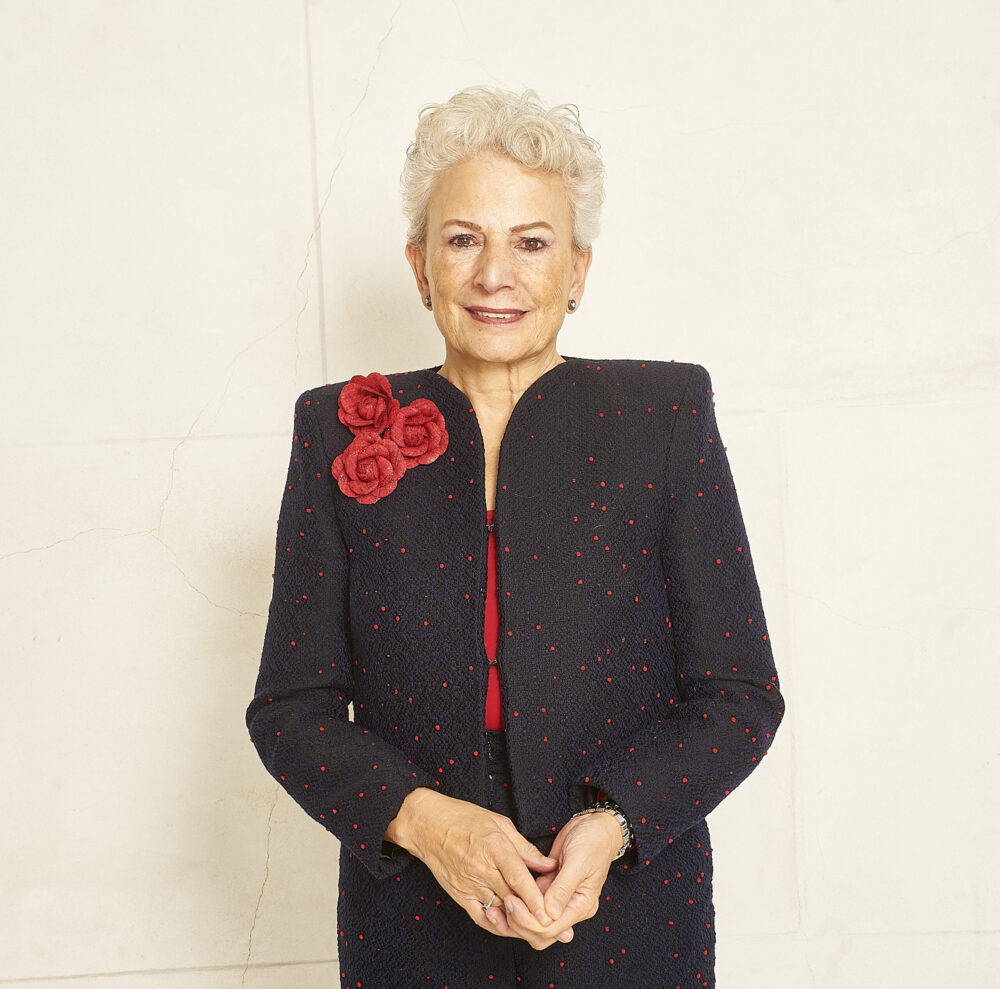
Europe has top-notch science, talent and a market of 450 million people. Even so, it is losing weight in the industry that sustains the digital economy. María Marced, former president of TSMC Europe, attributes this above all to fragmentation. And she believes that there is still room to correct the course.
Marced starred in the last webinar of the Bankinter Innovation Foundation’s semiconductor cycle, which followed up on the Future Trends Forum meeting held in June. Juan Moreno, CEO of the Foundation, led the conversation, which covered Marced’s career, the state of the industry and his work leading the advisory group that has contributed to the revision of the Chips Act.
Valenciana, a telecommunications engineer from the Polytechnic University of Madrid and a doctorate, has lived through the transformation of the sector from Intel, Philips Semiconductors, NXP and TSMC. She assumed the presidency of TSMC Europe in 2007 and participated in the negotiation of its factory in Dresden. She has worked in Spain, France, Germany, the United Kingdom and the Netherlands. She said that she would have liked to return to Valencia, but she did not find professional opportunities there.
An industry that creates wealth, accelerated by AI
For Marced, semiconductors are the basis of the digital economy. The ability to design and manufacture them determines which companies capture the value of new markets and which countries concentrate employment and investment. According to his data, the ten largest companies in the sector have a market capitalization of close to 16 trillion dollars, a figure that varies with the market.
Growth has come in waves: the PC, the internet, and the smartphone. The fourth is artificial intelligence, which Marced describes as an almost vertical curve. During the webinar, he cited forecasts that placed the market at around $2 trillion by 2036. The most recent data suggest that this threshold could be reached sooner. WSTS estimates sales in the first half of 2026 at $702 billion, up 102% from a year earlier. Incorporating these results into its spring scenario, maintaining the assumptions for subsequent periods, it estimates about $1.66 trillion for 2026 and about $2.1 trillion for 2027.
This vision is in line with what he already proposed in a previous article for the Foundation on semiconductors and European industrial strategy, where he placed AI at the edge (cars, robots and systems that process data outside the cloud) as the next big wave of demand.
From a global market to a fragmented market
The industry began with integrated companies: Philips or Siemens manufactured equipment and also its chips. Then the chain specialized. ASML became a key player in advanced lithography; TSMC developed a manufacturing model for third parties, the so-called foundries. Other companies, such as Infineon or NXP, maintain design and manufacturing capabilities. These models coexist in a chain where no region controls all the stages.
Specialization bolstered Asian manufacturing and American design, while Europe retained prominent positions in automotive, industrial, and equipment. Tensions between the U.S. and China introduce tariffs, export controls, and difficulties in maintaining common standards. Marced pointed to restrictions on advanced lithography equipment as an example of that fragmentation.
Europe is now looking to strengthen its technological autonomy. Cutting-edge AI accelerators use more advanced manufacturing processes than many automotive and industrial chips, and their high-volume production is concentrated outside Europe. The Future Trends Forum report on semiconductors explains the dependencies that run through this global chain.
From Chips Act 1.0 to 2.0
The first European Chips Act articulated three pillars: research and innovation, security of supply and monitoring of possible crises. Marced recognises the excellence of centres such as imec, Fraunhofer and CEA-Leti. Its criticism is directed at the difficulty of transforming this scientific capacity into a greater European industrial presence.
Aid to new factories, including the one in Dresden, responded to supply shortages exposed by the pandemic. In Marced’s view, this effort needs a closer connection with the sectors that will buy the chips and sustain investment.
Despite the aid, Marced warns that Europe continues to lose weight in the sector. He attributes this evolution to the growth of artificial intelligence, a market in which he considers the European industrial presence insufficient.
To correct this, the Commission brought industry together in an advisory group that Marced chaired. Its proposal, the European Chips Act 2.0. Industry Policy Blueprint, was presented in March 2026 at the dialogue on the implementation of the Chips Act. The Commission published its proposal for the Chips Act 2.0 on 3 June 2026, as reflected in the Foundation’s analysis of the shift from ambition to implementation.
The recommendations of the industrial group chaired by Marced propose connecting R+D with pilot lines, training and production. They also seek purchase commitments from end users, from telecommunications to automotive and defence. They are proposals from industry to guide European policy; the Commission’s legislative proposal has its own processing path.
Marced is confident in the size of the European market, but identifies fragmentation as the main obstacle to taking advantage of it. He used telecommunications as an example of a sector where dispersion between countries makes it difficult to compete with larger-scale companies.
Turning demand into industrial commitment
Demand occupied a large part of the webinar. Marced gave the example of Nokia and Ericsson and their dependence on US chip suppliers. The development of 6G opens, in his opinion, an opportunity to strengthen European design and manufacturing. The presence of end users such as Nokia, Bosch or Thales in the advisory group connects the proposals with specific industrial needs.
In Valencia, iPronics, a spin-off of the Universitat Politècnica de València, announced in September 2026 a round of 125 million dollars, with participation from NVIDIA. Its photonic technology seeks to improve connections between equipment in AI data centers, increasing communication capacity and reducing energy consumption. Marced interprets this link as an opportunity to get closer to large-scale customers. The materialization of this commercial opportunity will depend on the company’s execution, he stressed.
He also pointed to the opportunity to connect European AI chip design with new data centers. His argument is that sufficiently large purchasing commitments can attract advanced manufacturing. That possibility depends on whether technological and commercial projects prosper; when talking about new factories, he recalled that initiatives such as Japan’s Rapidus have yet to demonstrate their results.
If chips travel well, why link European demand to European manufacturing, Moreno asked. Marced highlighted security of supply and, above all, the creation of wealth and employment. In defence, he added, this industrial capacity is especially important: Europe needs its own technology to sustain its autonomy.
The Future Trends Forum report Semiconductors: critical capabilities for European competitiveness includes the same idea as a first priority: turning demand into industrial commitment through sectoral aggregation, multi-year contracts and strategic public procurement.
Clusters in the face of fragmentation
Marced proposes connecting companies and capacities that currently work in a dispersed way. In photonics, Spain participates in PIXEurope, the European pilot line led by ICFO. It also highlighted advanced power electronics, relevant for managing data centre energy. Cooperation can cross borders: he mentioned initiatives by European operators in satellite communications as an example of collaboration to gain scale.
From the laboratory to the factory
Collaboration between science and business already exists. Marced explained that TSMC, Samsung and Intel work with imec on pre-competitive research, sharing efforts before competing in the market. The difficulty is in converting that knowledge into products, companies and production capacity that grow in Europe.
Pilot lines help to go down this path: they allow prototypes to be manufactured, processes to be validated and risks to be reduced before large-scale production. The project for a future imec pilot line in Malaga expands on this commitment. For a startup, having a prototype facilitates conversations with customers and investors. Completing the design and ordering the first prototypes can require a high investment, especially in advanced nodes. The delivery of the final design to the factory is known as tape-out. Validating it before reduces uncertainty, although it does not eliminate industrial risk.
Then comes the challenge of scaling. Marced noted that Europe has capital, including Nordic and Dutch pension funds, but fragmentation and risk aversion make it difficult to mobilize it to tech companies. In his experience, closing a Series B or C can require so many conversations that companies end up seeking funding in the United States.
Talent across the chain
The talent shortage affects the entire chain, from engineering to factory technicians. Marced highlighted German vocational training and TSMC’s scholarship program, with several groups of students from the Technical University of Dresden. He said he found less response by offering similar opportunities in Valencia and Madrid. He also mentioned the willingness of Infineon and STMicroelectronics to support training. The challenge includes connecting students and schools to concrete industrial opportunities.
The lesson from Dresden
The Dresden factory shows how to bring together customers, technology partners and public support. ESMC is 70% owned by TSMC and 10% each by Bosch, Infineon and NXP. The 2023 announcement envisaged an investment of more than €10 billion and 40,000 300 mm wafers per month, with 28/22 and 16/12 nm processes. The Commission authorised German aid of €5 billion. The initial timetable placed the start of production in 2027; the Commission envisages full capacity in 2029. Its focus is on the automotive and industrial sectors. For Marced, it is a first step towards greater European manufacturing capacity.
The choice of Dresden was based on a previous ecosystem of manufacturers, suppliers, university and specialized personnel. Marced also highlighted access to water, electricity and land, and Saxony’s collaboration in permits. In Spain, he valued the institutional support for the IMEC project in Malaga. At the same time, he expressed concern about the regulatory conditions that data centers encounter: attracting demand requires that these projects can be executed.
Spain and the PERTE Chip
The PERTE Chip has a budget of 12,250 million euros and an initial horizon until 2027. Marced estimated during the conversation that some 3,000 million had been spent. He attributed the difficulties in attracting a large foundry to the lack of sufficient industrial demand. Among the actions underway, the Government awarded 17 Chip chairs in 2024, along with other research and development initiatives in the ecosystem.
Marced pointed to photonics and advanced power electronics as areas where Spain can build industrial positions. He called for continuity for the PERTE and warned of a concrete consequence: the chairs need funding to sustain their activity. Moreno linked this request to the conclusions of the forum. The critical capabilities report places the sector’s cycles on horizons of between 10 and 20 years, which require institutional stability and patient capital.
Leading in silicon to lead the future
Marced’s proposal connects concrete decisions: buyers who commit to European suppliers, prototypes that arrive at the factory, training linked to employment and financing that accompanies growth. Dresden shows how these conditions can be met. Extending them to new projects could allow a greater part of European demand to be translated into production, employment and its own technological capacity.
Expresidente de TSMC Europa